Bad credit car finance with Luv
Credit score not where you want it to be? Don’t worry — we’re here to help. These sections show you how car finance can still be possible, even with a bumpier credit history.
Our rates start from 11.9% APR, the rate you are offered will be based upon your individual circumstances.
Borrowing £8,700 over 5 years with a representative APR of 24.3% an annual interest rate of 21.9% (fixed) and a deposit of £0.00, the amount payable would be £239.88 per month, with a total cost of credit of £5,692.80 and a total amount payable of £14,392.80.
Luv Cars is a broker, not a lender.
Lender fees may apply, this is an example only.
Getting Car Finance With Bad Credit
If you’ve got a low credit score and need finance for a car, the search can feel overwhelming. But at Luv Cars, you don’t need to stress — we’re here to help. Our goal is to give everyone a fair shot at finding a deal, even if your credit history isn’t perfect.
We know that rebuilding your credit takes time, and securing steady work is often part of that journey. For many people, having a car is essential for getting to work — which is why being blocked by credit checks can feel extra frustrating.
That’s why we’ve made the process as straightforward as possible. By working with a wide panel of lenders, we aim to help people with all kinds of credit backgrounds find a car finance option that works for them.
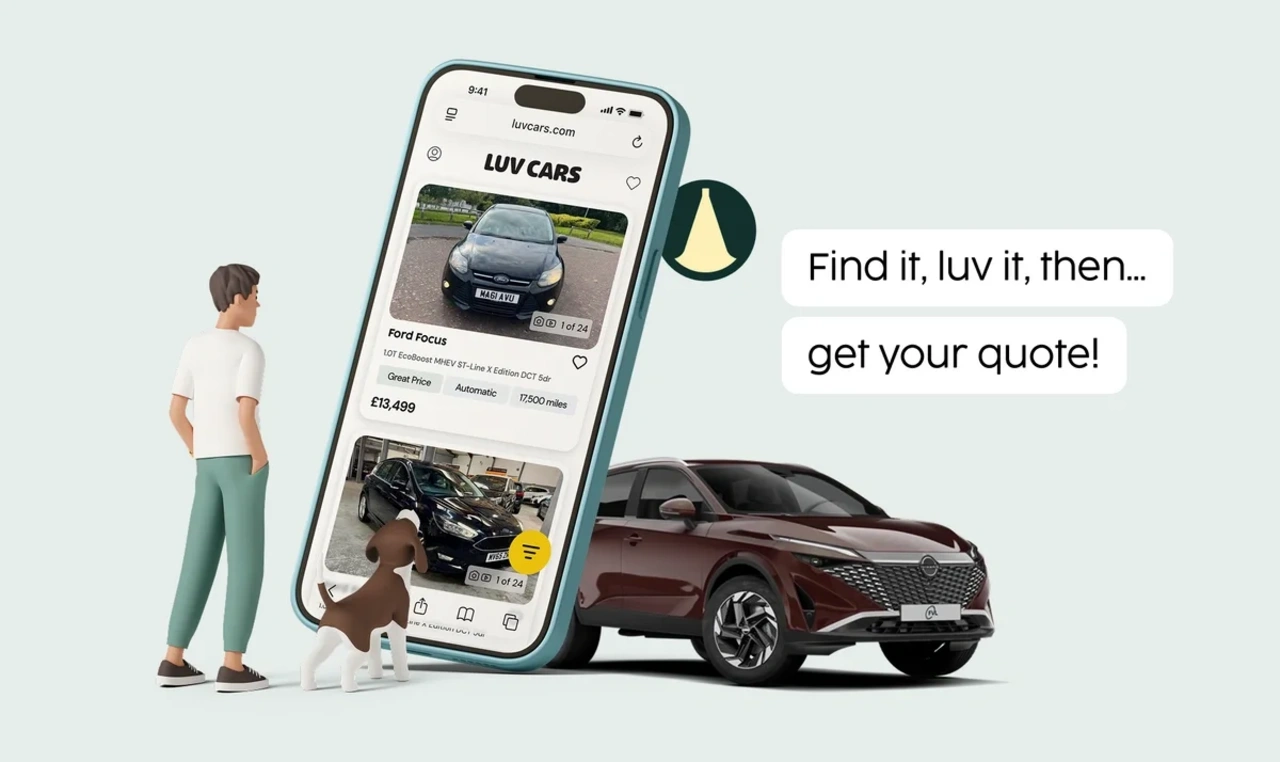
Over 100,000 cars to
Search and Save
LuvCarFinder™
What Does “Bad Credit” Actually Mean?
Bad credit usually comes from missed payments or past financial struggles. And because the UK’s three main credit reference agencies all use different scoring systems, there isn’t one universal definition of “bad credit.”
A credit score simply reflects how likely you are to be approved for credit. Higher scores show lenders that you’re more reliable. The good news? Your score can improve — it’s not fixed forever.
Here are the current “poor/very poor” bands used by each UK credit reference agency:
| Agency | Poor Score Range |
| Experian | 0–720 |
| Equifax | 0–438 |
| TransUnion | 0–566 |
What Causes a Bad Credit Score?
There are several reasons you might have a low score:
1. Missed or Late Payments
Missing payments on credit cards, loans or bills can lower your score.
2. CCJs, Defaults or IVAs
These remain on your report for six years and signal payment issues to lenders.
3. Bankruptcy or Debt Relief Orders
Formal insolvency solutions have a serious long-term impact on your credit rating.
4. Using Too Much Credit
Maxing out cards or overdrafts can show lenders you’re struggling to manage money.
5. Multiple Hard Credit Searches
Too many applications in a short time can make lenders view you as higher risk.
6. No Credit History
If you’ve never borrowed before, lenders have no record to judge affordability or reliability.
Can I Still Get Car Finance With Bad Credit?
Yes — you might be able to. At Luv Cars, we work with specialist lenders who assess every application individually, even if you’ve been turned down elsewhere.
Your past financial challenges don’t define you here. Whether you’ve had a CCJ, IVA, arrears, or missed payments, we’ll still explore options based on your circumstances. While we can’t guarantee approval, we’ll always do our best to find a lender willing to help.
All credit is subject to status.
Types of Bad Credit Car Finance
Even with bad credit, you may still have options. At Luv Cars, our lenders offer three main types of finance:
Hire Purchase (HP)
You pay for the full price of the car, plus interest, usually with a deposit upfront and fixed monthly payments. Once you’ve made the final payment, the car is yours.
HP payments are often higher each month than PCP but usually cheaper overall for people who want to own the car.
Personal Contract Purchase (PCP)
You pay smaller monthly amounts because you're only covering part of the car’s value. At the end, you can return the car, trade it in, or pay the balloon payment to keep it.
Great for keeping monthlies low, but expensive if you want to buy the car outright.
Refinancing
If you already have finance but are struggling with payments, refinancing could help reduce your monthly cost by spreading the remaining balance over a longer term. Some lenders may also offer better rates.
Keep in mind: spreading your loan for longer can lower your monthly payments but may increase the total interest paid overall.
All finance is subject to status and affordability.
Pros and Cons of Bad Credit Car Finance
| Pros | Cons |
| Spread the Cost No need to save the whole amount upfront — finance lets you get on the road sooner. |
Fewer Lender Choices You may not have access to the same range of offers as someone with good credit. |
| Improve Your Credit Score Staying on top of your repayments can help build your credit over time. |
Higher Interest Rates Lenders often charge more if your score is low. |
| Better Car Options Finance can make a newer or more reliable car affordable. |
Risk of Damaging Your Score Further Missing repayments can lower your score even more — and could lead to repossession. Always make sure you can comfortably afford the monthly payments. |
Apply in just 60 seconds
Comparing finance with Luv Cars is quick and easy.
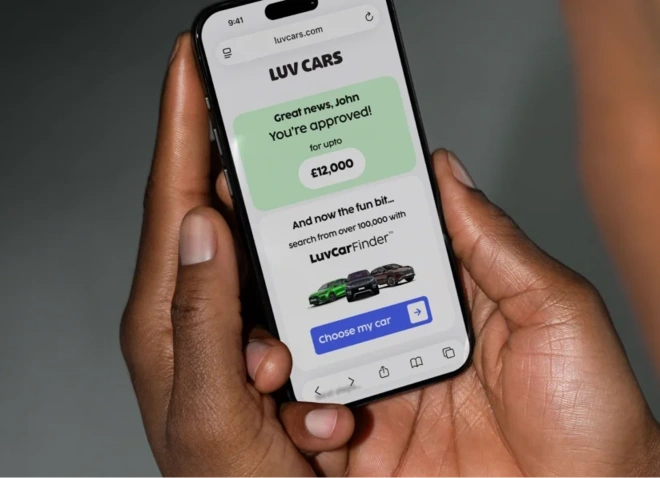
1. Get approved
Get your personalised car finance quote and approval in principle in minutes using our smart search tool.
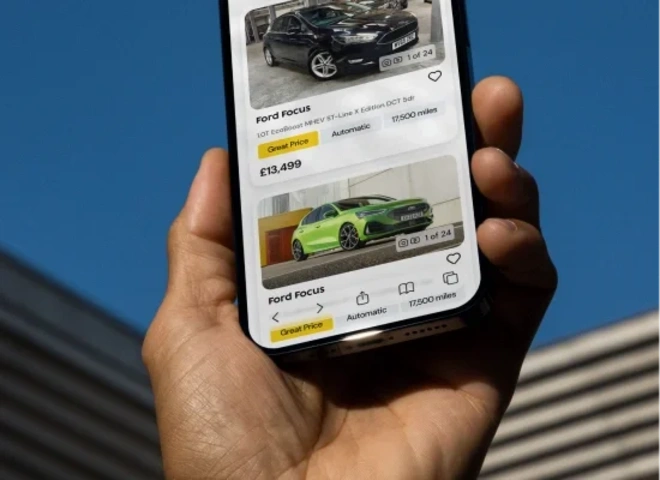
2. Choose your car
Once approved, find your car by using LuvCar finder. Showing you 1000’s of options from our approved dealers.
3. Drive away & luv it
We’ll sort everything out. You just turn up and drive away.
Why customers Luv us
Loading TrustPilot Reviews...
Frequently Asked Questions
What counts as bad credit?
Bad credit can mean a few things, and can include missed or late payments, County Court Judgements (CCJs), defaults on loans and credit cards, bankruptcy, or Individual Voluntary Arrangements (IVAs). You can even mean having little or no credit history, as banks and lenders don’t have enough information to base their decision on.
It’s also important to remember that there isn’t just one credit score – instead, there are three main Credit Reference Agencies or CRAs (TransUnion, Equifax, and Experian), with each one having a different score and a different way of calculating it.
How do I check my credit score?
You can check your credit report for free through apps like TotallyMoney for your TransUnion score, or CredAbility for your Equifax one – or directly with Experian.
Before you apply for any loan or credit, it's always worth checking your report. That way you can check that the information is correct and up to date, and see what might be holding you back. If you find an error, you can raise a dispute with the relevant agency.
Will applying for car finance affect my credit score?
When shopping around for car finance, it’s important to use tools like eligibility checkers which use a 'soft search', as they won't impact your credit score at all.
However, making a full application can, as lenders will use a 'hard search'. This can show on your credit file, and making multiple applications in a short space of time could affect your chances of borrowing in future.
What interest rates can I expect with bad credit?
If you have bad credit, it’s likely that you’ll have fewer options, and with higher Interest rates. That’s because lenders will see you as more of a risk. However, rates can vary depending on your circumstances, such as how much you want to pay, and over how long.
Shop around and compare your options, as you might find that using a specialist lenders and putting down a bigger deposit can help you get a better deal.
Do I need a deposit for bad credit car finance?
This will usually depend on your credit history, how much you would like to borrow, and the type of car finance you’re taking out. Some car finance lenders offer no-deposit deals, but it’s worth remembering that a deposit can often improve your chances of getting approved, and might help you get a lower interest rate.
What types of car finance are available with bad credit?
There are three main types of car finance available:
- Hire Purchase (HP)
- Personal Contract Purchase (PCP)
- Personal car loans
Each type of finance works in a different way.
With HP, you make fixed monthly payments over a set amount of time, and own the car when you've paid everything off.
With PCP, your monthly payments are often lower, but if you want to own the car at the end of the agreement, you'll need to make a final ‘balloon payment’.
With a personal loan, you borrow the money to buy a car, which you then own, and you make fixed monthly payments over the duration of the agreement.
Can I get car finance if I've been bankrupt?
It is still possible to get car finance after bankruptcy, but you’re likely to have fewer options, and you will probably pay a higher interest rate.
Will having a CCJ stop me getting car finance?
Having a County Court Judgement (CCJ) won't automatically stop you from getting car finance, but it can make it harder. When applying for car finance, lenders will look at how recent the CCJ is, how much it was for, and whether you’ve satisfied it (paid off).
If the CCJ is older, or you’ve settled it, you might have more options. There are some specialist lenders who will offer finance to people with CCJs, so make sure you compare all your options.
How can I improve my chances of approval?
There are a few things that can help your application, such as getting on the electoral roll at your current address, checking your credit report for incorrect information, and reducing how any existing debts where you can.
It's also worth thinking about the car you need, and can afford, and not the one you dream of. That's because being realistic and staying within your budget can mean you’re more likely to get accepted. If you can, save up for a deposit as this can show lenders that you're able to manage your money, and will reduce the total amount you need to borrow.
What happens if I miss a payment?
If you're struggling to keep up with repayments, then contact your lender right away. They might be able to offer support by adjusting your payment plan, which can give you some extra breathing space.
Remember that missed payments can damage your credit score, and might lead to your car being repossessed.
Can car finance help rebuild my credit score?
If you make all your payments on time, car finance can help you to build your credit score. That’s because it shows lenders you’re able to manage credit responsibly, even if you've had problems in the past.
Just make sure you can afford the payments before you commit, as missing them can damage your credit file.
How long will bad credit affect my ability to get finance?
Your credit file shows six years of borrowing history, meaning it’s important to start taking the right steps to improve it sooner rather than later.
Your more recent history will usually have more of an impact, so your situation can improve even before the six years are up.
What documents will I need to apply?
When applying for car finance the lender may request proof of identity, proof of where you live, and proof of how much you earn. If you're self-employed, you'll usually need to share tax returns or accounts for the past few years.
Are there any cars I should avoid with bad credit finance?
If you have bad credit, then it’s worth trying to stay within your budget, as the higher the loan amount, the harder it can be to get approved, and the more money it could cost you in the long term.
It’s also worth remembering that older cars with high mileage might also be harder to finance and insure, as they're seen as less reliable.