PCP Car Finance
If you want lower monthly payments and flexible options at the end of your agreement, PCP could be the perfect match. Luv Cars explains everything you need to know before you decide.
Our rates start from 11.9% APR, the rate you are offered will be based upon your individual circumstances.
Borrowing £8,700 over 5 years with a representative APR of 24.3% an annual interest rate of 21.9% (fixed) and a deposit of £0.00, the amount payable would be £239.88 per month, with a total cost of credit of £5,692.80 and a total amount payable of £14,392.80.
Luv Cars is a broker, not a lender.
Lender fees may apply, this is an example only.
What is PCP?
PCP (Personal Contract Purchase) is a flexible type of car finance that gives you options. When you reach the end of your agreement, you can choose to buy the car, hand it back, or trade it in for something new.
Unlike Hire Purchase, your PCP loan doesn’t cover the full cost of the car during the term. Instead, you finance the car’s expected depreciation and save the final “balloon payment” for the end if you decide you want to keep it. This usually means lower monthly payments compared to other finance options.
PCP can be a great fit if you like upgrading your car regularly, don’t rack up huge mileage, and want to keep your monthly costs on the lower side. Just remember: you’ll need to stick to the agreed mileage and look after the car to avoid extra charges at the end of the agreement.
Your monthly payment will depend on:
- Your deposit
- The car you choose
- The vehicle’s price
- The interest rate
- Your annual mileage
- How much the lender expects the car to be worth at the end
Over 100,000 cars to
Search and Save
LuvCarFinder™
What happens at the end of an agreement?
When your PCP agreement ends, you get to decide what happens next:
- Hand the car back
- Buy it by paying the one-off balloon payment
- Trade it in and use any equity as a deposit on a new PCP deal
It’s completely up to you.
What is a balloon payment?
The balloon payment is the final amount you’ll need to pay if you want to buy the car at the end of your PCP term. This figure is based on the Guaranteed Minimum Future Value (GMFV), which your lender agrees from the start.
If you can’t or don’t want to pay it all in one go, Luv Cars works with lenders who may offer refinance options to help spread the cost. Just keep in mind that paying it off over a longer period could mean a higher total cost overall.
How does PCP finance work?
PCP is designed to be simple. Think of it in three steps:
1. The deposit
Paying a deposit can lower your monthly payments — but £0 deposit options are also available.
2. The amount you borrow
You only borrow what the lender thinks the car will lose in value during your agreement, not the full cash price.
3. The balloon payment
If you want to keep the car at the end, you simply pay the balloon payment.
What are the pros and cons of PCP?
Here’s a quick look at the advantages and disadvantages of Personal Contract Purchase:
| Pros: | Cons: |
| Monthly payments are often lower than other car finance options | You won’t own the car unless you pay the balloon payment |
| You have flexibility at the end — buy, return, or trade in | Extra charges apply if you exceed your mileage limit or damage the car |
| Fixed monthly payments with no surprises | A deposit may be required |
| Access to newer cars more often |
Is PCP the right option for me?
PCP could be a good match if:
- You enjoy switching to a new car regularly
- You want lower monthly payments
- You like having options at the end of your agreement
Want more info? Head over to our guides where we break down PCP in full detail.
What’s the difference between Hire Purchase and Personal Contract Purchase?
Trying to choose between HP and PCP? Here are the key things to think about:
Do you want to own the car?
Both options can lead to ownership, but PCP gives you more flexibility.
- With HP, once you finish your payments and pay the small Option to Purchase fee, the car is yours.
- With PCP, you only own the car if you choose to pay the balloon payment at the end.
- If you’d rather have the option to return or trade in the car, PCP offers more freedom.
How much do you want to pay?
HP usually comes with higher monthly repayments, as you’re borrowing the full value of the car. PCP can be cheaper each month because you only finance the depreciation.
If keeping payments low is your priority, PCP might be the better choice.
Do restrictions apply?
PCP agreements come with mileage limits and condition checks. Go over your mileage or cause damage, and extra charges can apply. With HP, you’re unlikely to have mileage restrictions — great if you drive long distances regularly.
Prefer steady, fixed monthly repayments
Can I get a PCP loan?
To apply for PCP through Luv Cars, you’ll need to:
- Be over 18
- Have at least three years of UK address history
When you apply, we’ll aim to find you an approval in principle through our panel of lenders. This includes a soft credit check. Some lenders prefer applicants with a good credit score, which can improve your chances of approval.

Here’s how to get your finance
In 3 simple steps
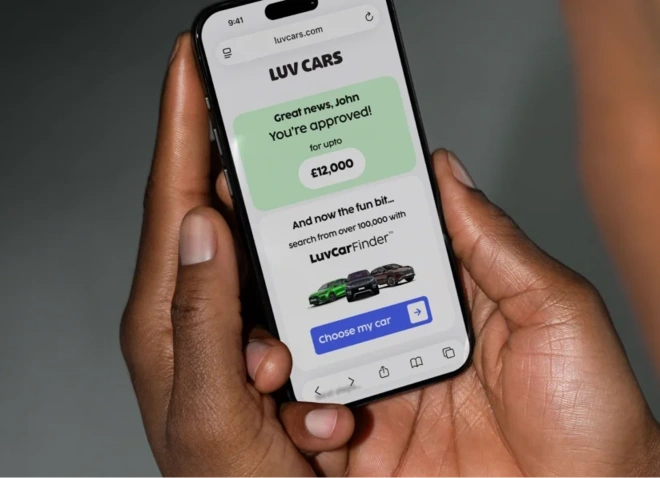
1. Get approved
Get your personalised car finance quote and approval in principle in minutes using our smart search tool.
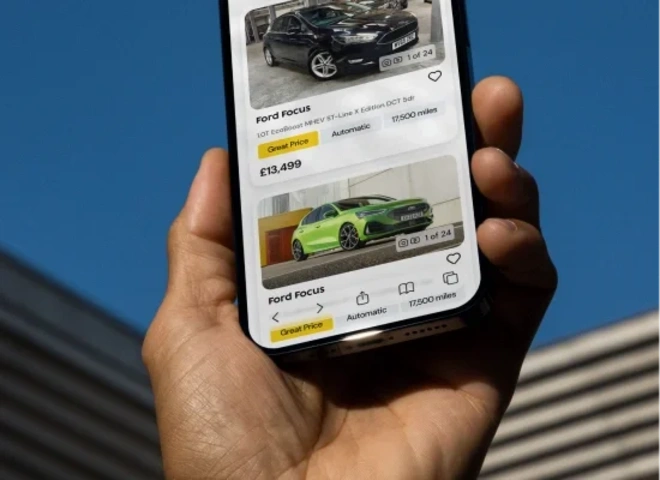
2. Choose your car
Once approved, find your car by using LuvCar finder. Showing you 1000’s of options from our approved dealers.
3. Drive away & luv it
We’ll sort everything out. You just turn up and drive away.
Why customers Luv us
Loading TrustPilot Reviews...
Frequently asked questions
Do I own the car on PCP?
Not automatically. To own the car, you’ll need to pay the balloon payment at the end. Otherwise, you can return it or use any equity towards a new deal.
Why are PCP monthly payments lower?
Because you’re only covering part of the car’s value — not the full amount — during the agreement.
Are there mileage limits with PCP?
Yes. Your lender will set a mileage allowance. Going over it can lead to extra charges.
What is a balloon payment?
It’s the optional final payment you make if you want to buy the car. It’s based on the car’s predicted value at the end of the agreement.
Can I end my PCP early?
Yes, but it can be harder than with HP because you often won’t reach the 50% voluntary termination point until later in the agreement.
Can I trade the car in at the end of a PCP?
Absolutely — if the car is worth more than the remaining finance, you can use that equity as a deposit on your next car.