Business car finance
Whether you’re self-employed or growing a fleet, business car finance can help keep your cash flow healthy. Here we break down the options so you can choose what suits your business best.
Our rates start from 11.9% APR, the rate you are offered will be based upon your individual circumstances.
Borrowing £8,700 over 5 years with a representative APR of 24.3% an annual interest rate of 21.9% (fixed) and a deposit of £0.00, the amount payable would be £239.88 per month, with a total cost of credit of £5,692.80 and a total amount payable of £14,392.80.
Luv Cars is a broker, not a lender.
Lender fees may apply, this is an example only.
Business Car Finance Made Simple
If you’re a business owner, sole trader, or self-employed, you might be thinking about financing a car through your business. Business car finance lets you spread the cost of a vehicle instead of paying for it all upfront — helping protect cash flow and even offering potential tax benefits.
At Luv Cars, we keep things easy. We search our panel of lenders to find options tailored to your business, help with the paperwork, and give you your own dedicated account manager to guide you from start to finish.
Over 100,000 cars to
Search and Save
LuvCarFinder™
Why Business Car Finance?
Business car finance allows your company to fund a vehicle through fixed monthly payments rather than one large upfront cost. This can make budgeting easier, especially if you’re a start-up or a small business trying to keep your cash free for other expenses.
Who Can Use Business Car Finance?
Business finance can suit anyone who needs a car for work and would like to fund it through their company. This includes:
- Business owners or directors who want to keep personal and business finances separate
- Self-employed workers who rely on a car for meetings, deliveries, or travel
- Sole traders wanting a flexible way to fund a vehicle without tying up cash
- Growing companies looking to maintain or expand their fleet
If your business relies on a vehicle regularly, spreading the cost through monthly payments could help stabilise cash flow and financial planning.
Your Business Car Finance Options
At Luv Cars, lenders on our panel may offer two main types of business finance:
Business Hire Purchase (HP)
You pay a fixed monthly amount plus interest over an agreed term. Once the final payment is complete, your business owns the vehicle outright. A great choice if ownership is the goal.
Business Personal Contract Purchase (PCP)
You make monthly payments plus interest, then choose at the end whether to:
- Pay a balloon payment to keep the car
- Return it
- Trade it in for another vehicle
PCP gives you more flexibility, but may cost more long-term.
How to Apply for Business Car Finance
Even with bad credit, you may still have options. At Luv Cars, our lenders offer three main types of finance:
Step 1 – Apply in Your Own Name
Begin your application in your personal name, as we don’t yet have a separate online form for business-only applications.
Step 2 – Tell Your Account Manager
Once you’ve been approved in principle, let your account manager know you’d like the finance to be in your business name.
Step 3 – Share Your Business Details
We’ll ask for a few details, such as your registered business name and number of employees.
Step 4 – We Handle the Rest
We’ll then search for business finance options from our lenders and guide you through the next steps.
Is Your Business Eligible?
Business car finance may be available to a wide range of companies, depending on your circumstances and whether the vehicle will be used for business purposes.
Whether you're a brand-new sole trader or running a long-established limited company, business finance could help you spread the cost of a car or van — subject to status.
Benefits and Drawbacks of Business Car Finance
| Benefits | Drawbacks |
| Spread the Cost Instead of paying the full amount upfront, you make manageable monthly payments — helpful when budgeting for other business needs. |
Monthly Costs Still Impact Cash Flow Even spread out, repayments are still ongoing expenses your business must plan for. |
| Keep Your Finances Clear Putting the car in your business name keeps your personal and company finances separate, making accounting simpler. |
Mileage & Condition Rules Some PCP deals have mileage limits or require the car to be returned in good condition; exceeding these may mean extra charges. |
| Potential Tax Advantages Depending on the finance type and usage, your business may be able to claim tax relief or VAT — reducing overall costs. |
Early Termination Can Be Costly Ending an agreement early may come with fees, so it’s important to plan ahead. |
Business vs. Personal Car Finance: What’s the Difference?
When choosing between business and personal finance, think about how you'll use the vehicle and who will be paying for it.
- Name on the agreement: Business finance is under your company; personal finance is under you.
- Tax advantages: Business deals may offer tax relief; personal finance does not.
- Usage: Business finance is for work-related driving; personal finance is for everyday use.
- Application: Business finance requires company details; personal finance can be quicker.
If the car is mainly for work, business finance may make more sense. If it’s mostly for personal driving, personal finance could be the better fit.
Here’s how to get your finance
In 3 simple steps
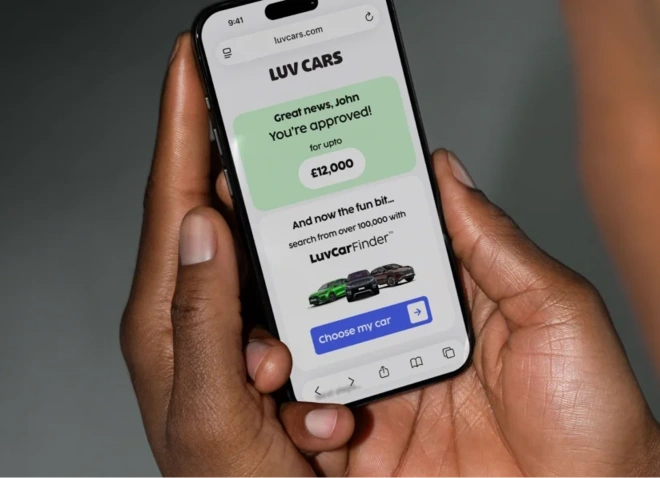
1. Get approved
Get your personalised car finance quote and approval in principle in minutes using our smart search tool.
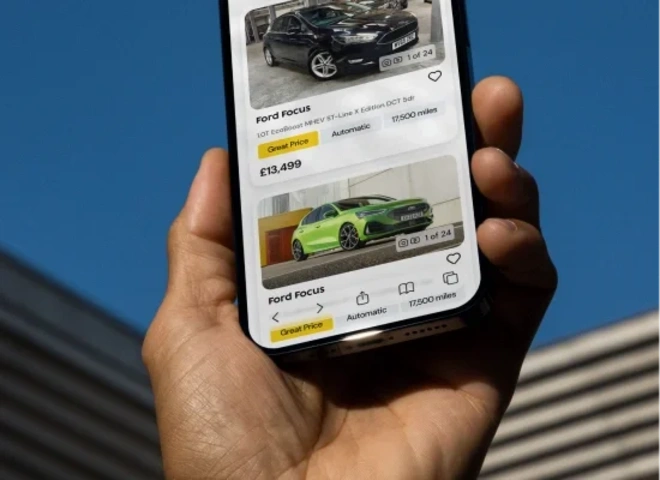
2. Choose your car
Once approved, find your car by using LuvCar finder. Showing you 1000’s of options from our approved dealers.
3. Drive away & luv it
We’ll sort everything out. You just turn up and drive away.
Why customers Luv us
Loading TrustPilot Reviews...
Frequently Asked Questions
Can any business apply for car finance?
In most cases, yes. Business car finance can be available to a wide range of businesses, including sole traders, limited companies, partnerships, freelancers, and self-employed professionals. Lenders will usually look at factors like your trading history, credit profile, and how the vehicle will be used. Whether you’re just getting started or already established, business car finance can help spread the cost of a car or van so you can keep your cash flow steady.
Do I apply in my business name straight away?
You’ll start your application in your personal name, simply because our online form doesn’t yet support business-only applications. Once you’re approved in principle, your dedicated account manager will update the application to your business details and guide you through the process. This step is completely normal, and it won’t delay your application — it just allows us to make sure we match you with the right lender for your business needs.
Can business car finance offer tax benefits?
Yes, it can — and this is one of the reasons many businesses choose this route. Depending on the type of finance and how the vehicle is used, you may be able to claim tax relief on monthly payments, offset running costs, or reclaim VAT if you’re VAT-registered. Benefits vary based on your business structure and agreement type, so it’s always a good idea to speak to an accountant, but business finance can offer significant financial advantages compared to personal finance.
Who owns the car in a business HP or PCP?
With Business Hire Purchase (HP), your business owns the car outright once the final payment (and any Option to Purchase fee) is made.
With Business PCP, ownership is optional — you’ll make monthly payments during the agreement, and at the end you can either pay the balloon payment to keep the vehicle, return it, or use any equity towards another car. HP suits businesses that want ownership, while PCP offers more flexibility and lower monthly costs.
Can I use the car for personal driving?
You can, but it may reduce some tax benefits and could affect your benefit-in-kind (BIK) tax liability. Many business owners use their vehicle for both work and personal driving, which is perfectly normal — you’ll just need to keep clear records so your accountant can calculate the right tax position. Business finance is primarily intended for work use, but personal use is often allowed as long as it’s documented correctly.
Do mileage limits apply to business cars?
Mileage limits usually apply to Business PCP agreements, just like with personal PCP. If you exceed your agreed annual mileage, the lender may charge an excess mileage fee at the end of your agreement. With Business HP, there are typically no mileage limits, making it a great option if you or your team drives long distances. Choosing between HP and PCP often comes down to how much flexibility you want and how far the car is likely to be driven each year.